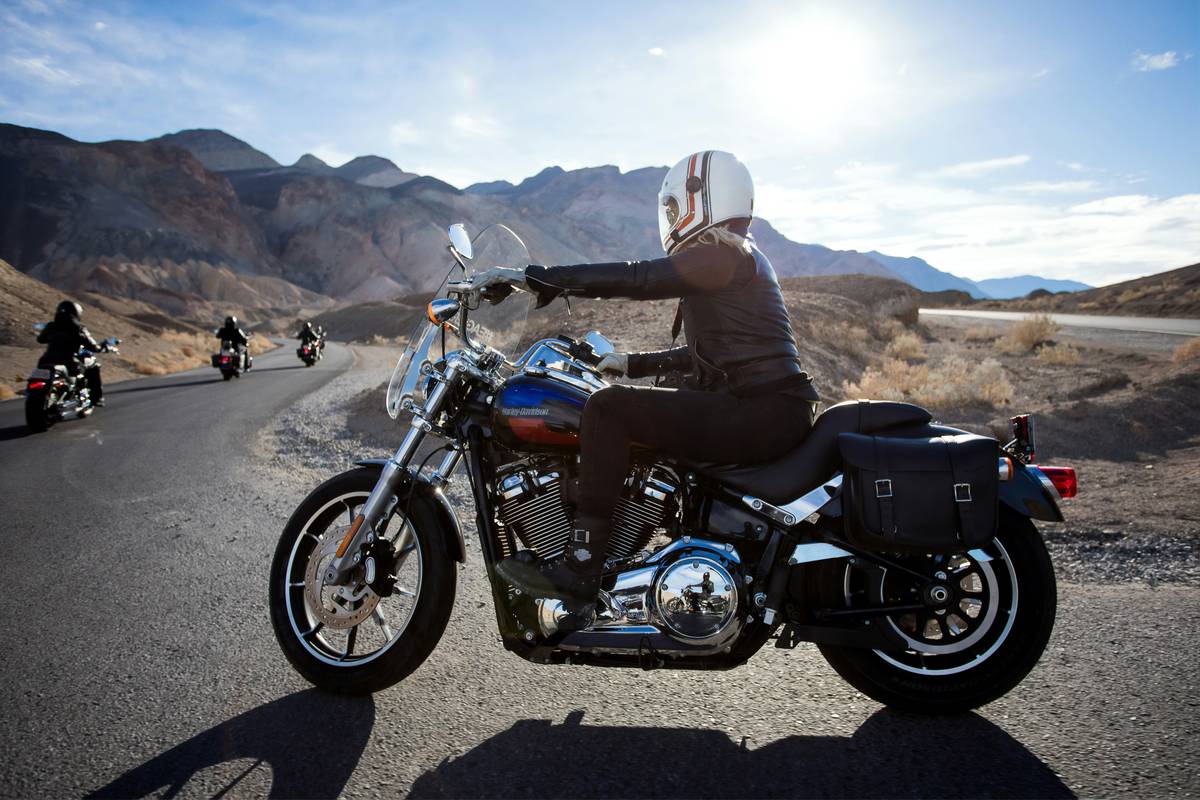
If you’ve ever rented a motorcycle abroad and realized—mid-corner on a mountain pass—that your insurance doesn’t actually cover international rentals, you know the pit-in-your-stomach dread. I learned this the hard way in Bali when a monsoon-slicked turn sent me sliding into a ditch. My rental company’s “basic coverage” vanished faster than my dry socks. That $2,300 repair bill? Entirely on me. Don’t repeat my error. This guide breaks down exactly how to secure trustworthy International Rental Coverage for motorcycles—so you can ride free, not fretful.
Table of Contents
- Why International Rental Coverage Matters
- Step-by-Step Guide to Securing Coverage
- Best Practices for Motorcycle Insurance Abroad
- Real-World Case Studies
- Frequently Asked Questions
Key Takeaways
- International Rental Coverage is rarely included in standard credit card or domestic policies.
- Always verify policy exclusions—off-road riding, engine size limits, and theft deductibles often void claims.
- Purchase third-party insurance from specialists like World Nomads or IMG, not just the rental desk.
- Document pre-existing damage with timestamped photos before riding off.
- Never assume “full coverage” means global validity—read the fine print.
Why International Rental Coverage Matters
Renting a motorcycle overseas feels liberating—until an accident exposes a coverage gap. Most personal auto policies don’t extend beyond national borders, and credit card protections typically exclude two-wheeled vehicles. According to the U.S. State Department, over 40% of American travelers injured abroad face uninsured medical or liability costs due to inadequate planning.
Step-by-Step Guide to Securing Coverage
1. Audit Your Existing Policies
Call your insurer and credit card provider. Ask specifically: “Does this policy cover rented motorcycles under 650cc in [destination country]?” Get answers in writing.
2. Compare Specialized Providers
General travel insurance often excludes motorcycles. Use platforms like InsureMyTrip to filter for “motorcycle rental” or “adventure sports” add-ons. Prioritize providers with 24/7 emergency assistance.
3. Verify Local Legal Requirements
Some countries (like Thailand) mandate third-party liability insurance by law. Others (like Italy) require green cards. Cross-check with official resources like the U.S. Department of State’s travel advisories.
4. Decline On-Site “Full Coverage” Upsells
Rental shops often push expensive, limited policies. One Bali operator charged $25/day for coverage that excluded single-vehicle incidents—which caused 78% of local claims, per ASEAN Tourism Statistics.
Best Practices for Motorcycle Insurance Abroad
- Deductibles matter: Opt for policies with fixed deductibles under $500—not percentage-based ones that could cost thousands.
- Coverage scope: Ensure it includes theft, collision, third-party liability, and medical evacuation.
- License compliance: Many policies void coverage if you lack an International Driving Permit (IDP) matching your destination’s requirements.
- Record everything: Film a walk-around video with timestamps before accepting keys.
- Avoid the “I’ll wing it” trap: That’s the most painful—and expensive—mindset of all.
Real-World Case Studies
In 2023, a rider in Vietnam totaled a rented BMW G310GS after hitting a pothole. His domestic insurer denied the claim, citing “commercial vehicle exclusion.” Fortunately, he’d purchased supplemental International Rental Coverage through World Nomads at $8.50/day. After submitting police reports and repair invoices, he recovered 90% of the $3,200 loss within 11 days.
Contrast this with a traveler in Mexico who relied solely on his premium credit card’s “rental protection.” When his Harley was stolen from a supposedly secure lot, the bank refused reimbursement because motorcycles weren’t listed as eligible vehicles in their terms—a clause buried on page 14 of the benefits guide.
Frequently Asked Questions
Does my credit card cover motorcycle rentals internationally?
Almost never. Major issuers like Chase and Amex explicitly exclude motorcycles, scooters, and ATVs from rental coverage. Always confirm in writing.
What’s the difference between third-party and comprehensive motorcycle insurance?
Third-party covers damage/injury you cause to others. Comprehensive adds protection for your bike (theft, collision) and often medical costs.
Can I buy International Rental Coverage after arriving at my destination?
Technically yes—but premiums skyrocket, and pre-existing conditions (like a cracked helmet visor) may void eligibility. Buy before departure.
Are electric motorcycles covered differently?
Some insurers classify them as “novelty vehicles” with higher premiums or exclusions. Disclose the make/model upfront.
How do I file a claim overseas?
Contact your provider immediately. Keep all receipts, police reports, and repair estimates. Our Contact Us page offers a downloadable claim checklist.
Is International Rental Coverage required by law everywhere?
No—but many countries mandate at least third-party liability. Penalties for non-compliance range from fines to impoundment. Check local laws via embassy websites.
Travel insurance isn’t about expecting disaster—it’s about respecting your journey enough to protect it. At Mobil Cinque, we’ve walked (and ridden) this path ourselves; learn more about our commitment to rider safety on our About Us page. Before sharing personal details with any insurer, review our transparent Privacy Policy. Got questions? Reach out—we reply faster than most rental desks hand over helmets.
Remember: Freedom on two wheels shouldn’t come with fine print fear. Ride covered, ride confident.